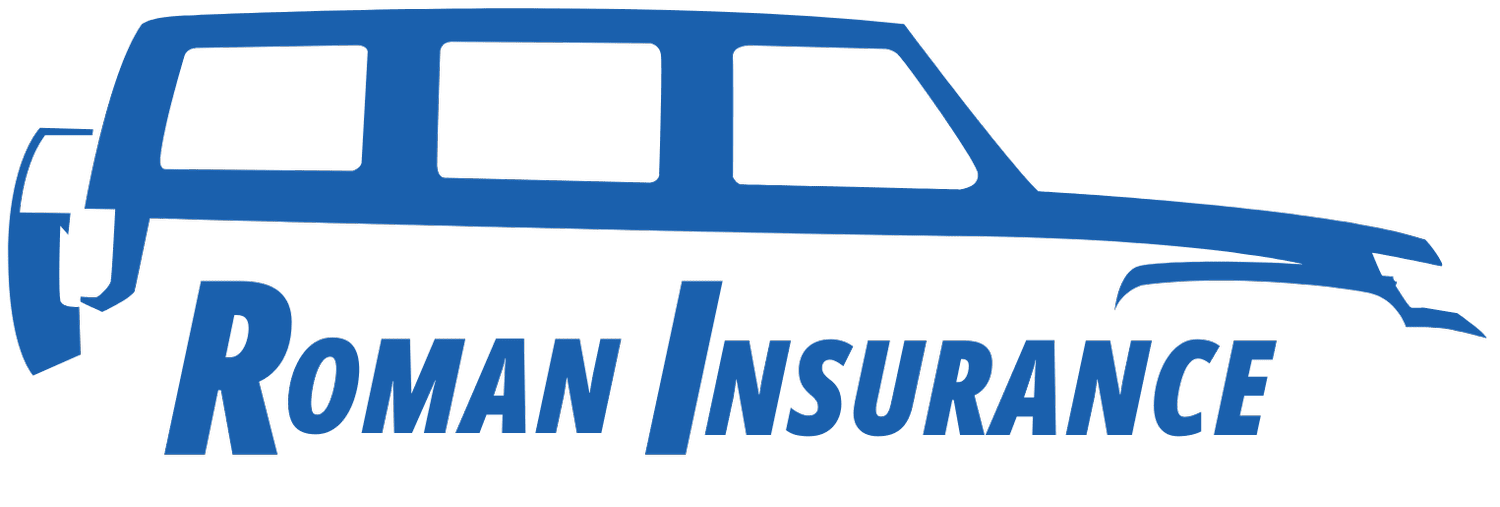
Which boat insurance companies lead the pack in 2026?
Progressive, BoatUS, Foremost, and Allstate are the strongest boat insurance companies available to U.S. boat owners in 2026. Each brings something different: Progressive leads on price, BoatUS on membership perks, Foremost on specialty vessel coverage, and Allstate on bundling value for homeowners who also own boats. If you’re in West Tennessee, Roman-insurance offers Allstate boat policies with the kind of local, personalized service that online-only quotes simply can’t replicate.
| Provider | Best For | Coverage Options | Pricing/Value | Membership Benefits | Reputation |
|---|---|---|---|---|---|
| Progressive | Affordability | Broad standard coverage | Starts at approximately $100/year | None | Strong, widely available |
| BoatUS | Membership perks | Liability, physical damage, towing | Competitive | Unlimited towing, slip access | Excellent marine focus |
| Foremost | Specialty vessels | Fishing boats, yachts, PWC | Mid-range | Limited | Strong specialty reputation |
| Allstate | Bundling discounts | Full coverage suite | Best with bundles | Multi-policy savings | A+ financial strength |
| Roman-insurance | Local West TN owners | Allstate-backed full suite | Competitive + local discounts | Multi-policy bundling | Trusted local agency |
Table of Contents
- A closer look at the top marine insurance providers
- What does a standard boat insurance policy actually cover?
- What drives the cost of boat insurance?
- How to choose the right boat insurance company
- How policy terms and conditions differ across providers
- Roman-insurance covers your boat the right way in West Tennessee
- Key Takeaways
A closer look at the top marine insurance providers
Progressive
Progressive is the go-to for boat owners who want solid coverage without paying a premium for it. Progressive offers boat insurance starting at approximately $100 per year, making it one of the most accessible entry points in the market. Discounts for completing a boating safety course and paying your premium in full push that number even lower. Coverage includes physical damage, liability, and personal effects, and the online quoting process is fast. The tradeoff is that Progressive operates through a largely automated system, so if you want someone to walk you through policy nuances, you’ll need to seek that out.
Key features:
- Liability and physical damage coverage
- Safety course and paid-in-full discounts
- Online quote in minutes
- Available nationwide
BoatUS
BoatUS is the only major provider that pairs insurance with a full membership program. BoatUS membership includes unlimited towing and access to transient slips, which matters enormously if you spend significant time on the water. The insurance itself covers liability, physical damage, and on-water towing, but the membership layer is what separates it from every other option on this list. Boat owners who dock frequently or cruise long distances get real, tangible value beyond the policy itself.
Key features:
- Unlimited towing included with membership
- Transient slip access
- Liability and physical damage coverage
- Strong marine-specific claims handling
Foremost
Foremost specializes in the kinds of boats that standard carriers sometimes struggle to cover well: fishing boats, personal watercraft, pontoons, and yachts. Top boat insurers like Foremost offer policies built around specialty vessels, which means coverage terms are written with those boats’ actual risks in mind rather than adapted from a generic template. Pricing sits in the mid-range, and the company’s long track record in marine insurance gives it credibility with agents and adjusters alike.
Key features:
- Specialty coverage for fishing boats, PWC, yachts
- Agreed value and actual cash value options
- Liability and physical damage
- Experienced marine claims team
Allstate
Allstate’s strength is integration. If you already carry Allstate homeowners or auto insurance, adding a boat policy can meaningfully reduce your total premium across all three. The coverage suite is complete: liability, physical damage, medical payments, uninsured boater, and personal effects. Allstate holds an A+ financial strength rating from AM Best, which matters when you’re filing a claim after a serious incident. It’s not the cheapest standalone option, but for existing Allstate customers, the bundled value is hard to beat.
Key features:
- Full coverage suite including uninsured boater
- Multi-policy discounts with home and auto
- A+ AM Best financial strength rating
- Available through local agents for personalized service
Roman-insurance (Allstate agent, West Tennessee)
Roman-insurance brings Allstate’s full boat insurance portfolio to West Tennessee boat owners, with a local agent who knows the area’s lakes, marinas, and coverage requirements. Rather than navigating an automated quote system, you get a real conversation about your boat, how you use it, and what coverage actually fits. For high-value boat owners near the 38002 area, that kind of personalized guidance often surfaces discounts and coverage combinations that online tools miss entirely. Roman-insurance also helps clients bundle boat and home insurance for maximum savings.
Key features:
- Allstate-backed coverage with local agent support
- Multi-policy bundling with home, auto, and life
- Personalized coverage review for West Tennessee boaters
- Focus on high-value residential and watercraft clients
What does a standard boat insurance policy actually cover?
Most boat insurance policies include a core set of protections, but the details vary significantly between providers. Knowing what’s standard versus what requires an add-on saves you from discovering a gap after an incident.
Core coverage types you’ll typically find:
- Liability: Covers bodily injury and property damage you cause to others on the water. Most marinas require proof of liability coverage before allowing a boat to dock.
- Physical damage: Pays for repairs or replacement of your boat after a collision, fire, theft, or vandalism.
- Uninsured/underinsured boater: Protects you when another boater causes an accident and carries no insurance.
- Medical payments: Covers medical costs for you and your passengers after an on-water accident, regardless of fault.
- On-water towing: Pays for emergency towing if your boat breaks down. Some providers include this; others charge extra.
- Trailer coverage: Extends protection to your boat trailer while in transit or storage.
- Personal effects: Reimburses lost or damaged personal items aboard, such as fishing gear, electronics, or clothing.
Boat insurance is mandatory in only a handful of states, but lenders almost always require comprehensive and liability coverage if you’re financing a vessel. Even where it’s not legally required, skipping coverage on a boat worth tens of thousands of dollars is a risk few owners can actually afford to take.
Common exclusions to watch for:
- Wear and tear or mechanical breakdown
- Damage from racing or commercial use
- Fuel spill liability (sometimes requires a separate rider)
- Coverage outside agreed navigational limits
What drives the cost of boat insurance?
Boat insurance premiums vary more than most people expect, and the spread between the cheapest and most expensive policies for similar boats can be substantial. Completing a boating safety course is one of the most reliable ways to lower your rate, and it’s a discount most major carriers offer.
Factors that affect your premium:
- Boat value and type: A $15,000 fishing boat and a $150,000 yacht carry very different risk profiles.
- Engine horsepower: Higher horsepower means higher speed, which correlates with higher accident risk and higher premiums.
- Age of the vessel: Newer boats often qualify for better rates; older boats may face surcharges or coverage restrictions.
- Location and usage: Coastal saltwater use typically costs more than freshwater lake use. Year-round use costs more than seasonal.
- Storage method: Boats stored in a locked facility or on a lift cost less to insure than those left in open water year-round.
- Your boating history: Prior claims or violations raise rates, just as they do with auto insurance.
- Loan status: If you’re financing, your lender will dictate minimum coverage levels, which affects your total cost.
Rate snapshot: Progressive offers boat coverage starting at approximately $100 per year for smaller, lower-horsepower vessels with clean records. Premiums for larger or higher-value boats run considerably higher.
Bundling your boat policy with an existing home or auto policy is one of the most effective ways to reduce overall costs. Most major carriers, including Allstate, offer multi-policy discounts that can take a meaningful percentage off each policy in the bundle. For West Tennessee boat owners already carrying Allstate home or auto coverage through Roman-insurance, adding a boat policy to that bundle is often the single fastest way to lower total insurance spending.
How to choose the right boat insurance company
The right insurer isn’t always the one with the lowest quote. A policy that saves you $50 a year but leaves you underinsured after a fuel spill or a collision with an uninsured boater is a bad deal. Here’s how to evaluate your options clearly.
What to look for:
- Marine-specific expertise: Marine insurance claims involve complexities like environmental liability and fuel spill damages that standard property claims don’t. Insurers with dedicated marine claims teams handle these situations far better than general carriers.
- Financial strength ratings: Check AM Best ratings before committing. An A or A+ rating means the company can pay claims even after a major weather event that generates thousands of simultaneous claims.
- Customer reviews on claims handling: A carrier’s reputation during the quote process tells you almost nothing. Read reviews specifically about how claims were handled.
- Customizable policy options: Generic quotes often miss coverage gaps specific to your boat type or usage. Look for carriers or agents who ask detailed questions before quoting.
- Bundling opportunities: If you own a home or carry auto insurance, bundling with the same carrier almost always produces savings. Check the home and auto bundle options available through your current insurer first.
- Navigational territory: Make sure your policy covers where you actually boat. Some policies restrict coverage to inland waters only; others extend to coastal or offshore use.
Questions to ask before you sign:
- Does this policy cover agreed value or actual cash value?
- What are the navigational limits?
- Is on-water towing included or an add-on?
- How are fuel spill cleanups handled?
- What’s the claims process, and how long does resolution typically take?
Pro Tip: Working with a local independent agent like Roman-insurance gives you access to Allstate’s full boat insurance portfolio plus a real conversation about your specific boat, marina, and usage patterns. That conversation often surfaces discounts and coverage combinations that automated online quotes never flag, including multi-policy savings when you bundle boat liability coverage with your existing home or auto policy.
For regional coverage options, watercraft coverage specialists in neighboring states like Louisiana can also offer useful benchmarks when comparing policy terms across the Gulf South region.
How policy terms and conditions differ across providers
Reading two boat insurance policies side by side reveals how much variation exists beneath similar-sounding coverage names. The differences that matter most aren’t always obvious from a summary page.
Agreed value vs. actual cash value is the biggest one. Agreed value policies pay the amount you and the insurer agreed on when the policy was written, with no depreciation deducted. Actual cash value policies subtract depreciation, which can leave you significantly short on a total loss. Foremost and BoatUS both offer agreed value options; Progressive defaults to actual cash value on many of its standard policies.
Navigational limits define where your coverage applies. A policy written for freshwater lake use in Tennessee may not cover you if you trailer the boat to the Gulf Coast for a fishing trip. Always confirm the geographic scope before assuming you’re covered.
Lay-up periods are clauses some insurers use to reduce premiums during months when the boat is in storage. If you boat year-round or in a warm climate, make sure a lay-up clause isn’t quietly built into your policy.
Deductible structures also vary. Some carriers offer a single flat deductible; others apply separate deductibles for different types of claims (collision vs. theft vs. storm damage). A policy with a low premium but three separate $500 deductibles can cost more out of pocket after a complex incident than a slightly pricier policy with one flat deductible.
Exclusions for racing, commercial use, and intentional damage are standard across virtually every carrier. Less obvious exclusions include coverage gaps for boats used as a primary residence, damage caused by marine organisms (zebra mussels, for example), and losses that occur outside the policy’s stated navigational territory. Comparing the exclusions section of competing policies, not just the coverage summary, is where the real differences show up.
For a broader look at how to compare coverage across personal lines, comprehensive insurance products from regional specialists can provide useful context on what a well-structured bundle looks like.
Roman-insurance covers your boat the right way in West Tennessee
If you’ve spent time comparing quotes online, you’ve probably noticed that automated systems treat every boat the same. Roman-insurance works differently. As a local Allstate agency serving West Tennessee, particularly within the 38002 area, Roman-insurance builds boat policies around how you actually use your vessel, whether that’s weekend fishing on a lake, keeping a pontoon at a marina, or insuring a higher-value boat that deserves more than a generic quote.
The practical advantage is straightforward: Roman-insurance clients who already carry Allstate home or auto policies can bundle their boat coverage into that existing relationship and typically see savings across every policy in the bundle. You get Allstate’s A+ financial strength and nationwide claims network, plus a local agent who picks up the phone and knows your name. For West Tennessee boat owners who want real coverage and real service, that combination is worth more than the cheapest rate you’ll find on a comparison site. Reach out to Roman-insurance directly to get a personalized boat insurance quote and find out exactly what bundling could save you.
Key Takeaways
The best boat insurance company for you depends on your vessel type, usage, location, and whether you can bundle with existing policies for meaningful savings.
| Point | Details |
|---|---|
| Progressive leads on price | Coverage starts at approximately $100 per year for smaller boats, with discounts available for safety courses and full payment. |
| BoatUS offers unique membership value | Unlimited towing and transient slip access go beyond what standard insurance policies provide. |
| Policy terms vary significantly | Agreed value vs. actual cash value, navigational limits, and deductible structures differ widely across providers. |
| Bundling cuts total premium costs | Combining boat, home, and auto policies with one carrier consistently produces multi-policy discounts. |
| Roman-insurance serves West Tennessee | Local Allstate agency offering personalized boat policies with bundling options for high-value boat owners near 38002. |